 NMLS 900669
You can reach the equity you already have, grow your home's value before you list it, and buy the next house before this one sells. Three programs make it work. Here is how they fit together.
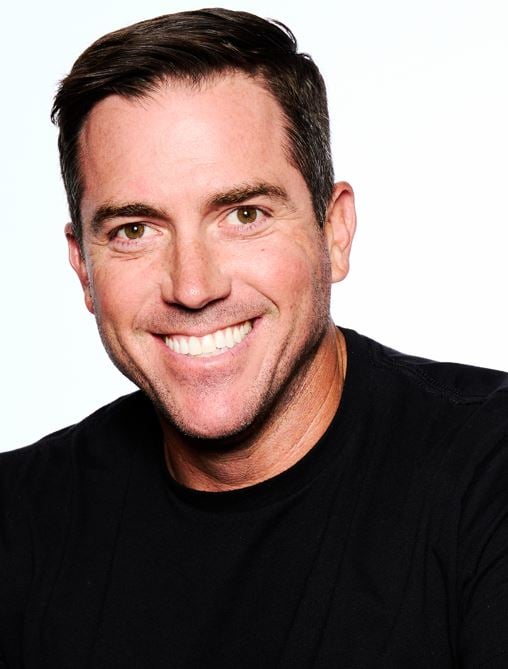 Sean Herrero
Regional Vice President, NMLS 900669
CrossCountry Mortgage, Danville CA
Most homeowners who want to move say some version of this.
The equity you already own can handle all three. It is a question of sequence.
Each one sets up the next. Run them in sequence and you list a better home and buy without waiting.
A home equity line of credit lets you draw on the value you have already built and put it into the updates that raise what your home is worth. The application is fast and built to be simple, and funds can be available in as little as five days, so the work can actually start.
Once the improvements are done, the home is worth more than it was. A bridge loan lets you access that larger pool of equity and turn it into the down payment on your next house, before the current one sells.
The buy before you sell program is designed so your current housing payment does not sink your qualification for the next one. That means a stronger offer on the home you want, without a home sale contingency and without waiting on a buyer's timeline.
Doing it the usual way
Doing it in this order
Walked us through every cost and every scenario with live numbers on the screen, so we understood exactly what we were choosing and why.
Freddie S.Detailed, clear about the process from day one, and quick to respond every time something came up. A complicated purchase was made to feel simple.
Kaitlin C.After being given the runaround by other lenders, the team stepped in and got it done. Easy application, and we were always kept updated.
Yashada D.
Regional Vice President, CrossCountry Mortgage, NMLS 900669
Sean works with California homeowners on the financing side of moving: reaching equity, bridging the gap between two homes, and structuring a purchase so it does not depend on a sale closing first. The meeting is a conversation about your situation and whether this sequence fits it.
No cost, no application required to talk it through.
The idea is that your existing equity funds the improvements and the down payment rather than your savings. Whether that works in your case depends on your equity, income, and credit, which is what the meeting covers.
That gap is what bridge financing is designed for. The timeline and the carrying costs get mapped out up front so you know what you are signing up for.
That is a question for a local real estate agent who knows what buyers in your neighborhood pay a premium for. Sean can point you to agents he works with, or work alongside the agent you already have.
No. They are designed to work together, but plenty of homeowners only need one or two of them. The meeting sorts out which parts apply to you.
A walk through your numbers and the sequence, in plain language, so you can decide whether it is worth pursuing. There is no obligation and no cost.
Grab a time directly on Sean's calendar, or send your contact information and he will reach out to schedule.
Open calendar, real availability, no back and forth.
Book my meetingOr send your details
Takes about 20 seconds
Sean will reach out shortly to schedule. To move faster, book a time on his calendar or call 925.575.0637 right now.